BUSINESS
How Mobile Payments Turned Into Fast Cashouts

It’s no secret that mobile payments have revolutionized how you handle money, turning lengthy transactions into instant cashouts. With just a few taps on your phone, you can send, receive, or withdraw funds faster than ever before. Whether you’re splitting bills, paying for services, or accessing your earnings, mobile platforms streamline the process, putting financial control at your fingertips. This shift has made traditional banking delays a thing of the past, giving you the speed and convenience you need in today’s fast-paced world. Here’s how mobile payments transformed into the quick cashouts you rely on daily.
The Rise of Mobile Payments
For years, mobile payments have transformed how you handle money, shifting transactions from physical wallets to your smartphone. With apps like Apple Pay, Venmo, and PayPal, you can now send or receive funds instantly, eliminating the need for cash or cards. This convenience has made mobile payments a staple in your daily life, whether you’re splitting a bill or shopping online. The seamless integration with banking systems ensures your money moves faster than ever, paving the way for quick cashouts and financial flexibility.
Evolution of Payment Technologies
At the heart of mobile payments lies a rapid evolution in technology. From magnetic stripes to NFC and QR codes, each innovation has made transactions smoother for you. Your phone now acts as a digital wallet, storing payment details securely and enabling contactless purchases. Biometric authentication, like fingerprint or facial recognition, adds an extra layer of security, ensuring your transactions are both fast and safe. These advancements have redefined how you interact with money, making traditional methods feel outdated.
Growth of Peer-to-Peer Transactions
For peer-to-peer (P2P) platforms, the rise of mobile payments has been a game-changer. You no longer need to rely on bank transfers or checks to send money to friends or family. Apps like Zelle and Cash App let you transfer funds in seconds, often with just a phone number or email. This shift has made splitting expenses or paying freelancers effortless, putting control of your finances directly in your hands.
In addition, P2P transactions have expanded beyond personal use, becoming a tool for small businesses and gig workers. You can now invoice clients or receive payments instantly, bypassing traditional banking delays. This growth has fueled a culture of instant gratification, where your money is always within reach, ready to be spent or saved as you see fit.
Instant Small Payment Withdrawals
There’s no waiting around with mobile payments—your small withdrawals hit your account instantly. Whether you’re splitting a bill, cashing out gig earnings, or transferring funds to a friend, platforms like Venmo, Cash App, and PayPal make it seamless. You get immediate access to your money, eliminating the delays of traditional banking. This speed transforms how you manage your finances, turning mobile wallets into your go-to for fast, frictionless transactions.
Convenience and Accessibility
Among the biggest advantages of mobile payments is how effortlessly you can access your funds anytime, anywhere. You don’t need to visit a bank or ATM—just a few taps on your phone, and your money is on the way. Whether you’re paying for coffee or sending rent money, the process is streamlined for your convenience. This accessibility ensures you’re always in control of your finances, even on the go.
Impact on Consumer Behavior
Impact is clear: instant withdrawals have reshaped how you spend and save. You’re more likely to make impulsive purchases or split costs instantly, knowing funds are available right away. The immediacy of mobile payments encourages smaller, frequent transactions, altering your budgeting habits. Over time, this shift can lead to a more fluid relationship with money, where waiting feels outdated.
Considering this behavioral shift, you might notice how mobile payments blur the line between spending and saving. The ease of moving money can lead to less deliberate financial decisions, making it necessary to track your transactions. While convenience is unmatched, staying mindful of your spending patterns helps you maintain control over your financial health.
Cashing out small payments – A Cultural Perspective
Any society’s financial habits reflect its cultural values, and South Korea’s embrace of mobile payments is no exception. The rapid adoption of 소액결제 현금화 Cashing out small payments highlights a blend of tech-savviness and a desire for liquidity. You see this practice thrive in a culture where convenience and speed are prioritized, allowing users to bypass traditional banking hurdles. Yet, it also raises questions about financial responsibility and the risks of informal cash flow systems.
Understanding the Practice
By converting small mobile payments into cash, you tap into a system designed for quick access to funds. This method often involves reselling digital vouchers or prepaid credits, turning non-cash assets into spendable money. While it offers flexibility, you should be aware of the fees and potential legal gray areas. The practice is widespread, but understanding its mechanics helps you navigate it wisely.
Implications for Financial Freedom
Beside the immediate convenience, 소액결제 현금화 can empower you with faster liquidity, especially if traditional banking feels restrictive. However, relying on it too heavily may lead to unstable financial habits. You gain short-term flexibility but risk long-term security if not managed carefully.
Cultural attitudes toward debt and spending play a role here. In South Korea, where credit systems are robust yet scrutinized, you might find this workaround appealing. Yet, it’s worth considering how these practices align with your broader financial goals and the societal norms shaping them.
Security Concerns in Fast Cashouts
Unlike traditional payment methods, fast cashouts via mobile payments can expose you to risks like unauthorized transactions or data breaches. Cybercriminals often target quick-transfer systems, exploiting weak authentication or phishing scams to access your funds. While convenience is a priority, ensuring your financial safety requires understanding these vulnerabilities and taking proactive steps to protect your money.
Fraud Prevention Measures
Security starts with choosing platforms that use multi-factor authentication and encryption to safeguard your transactions. Enable notifications for every transaction, so you’re alerted to any suspicious activity. Regularly update your apps and avoid sharing sensitive details over unsecured networks to minimize your exposure to fraud.
Consumer Awareness
After adopting mobile payments, staying informed about common scams is your best defense. Be cautious of unsolicited links or requests for personal information, as these are often tactics used by fraudsters. Verify the legitimacy of payment requests before approving them to avoid falling victim to social engineering attacks.
It also helps to familiarize yourself with your provider’s fraud policies, so you know how to report issues and recover lost funds. By staying vigilant and educating yourself on emerging threats, you can enjoy the speed of fast cashouts without compromising your financial security.
The Role of Financial Institutions
Once again, financial institutions play a pivotal role in shaping how mobile payments evolve into fast cashouts. By integrating advanced security measures and streamlining transaction processes, banks and credit unions ensure your money moves swiftly and safely. They also set the regulatory framework that balances innovation with consumer protection, giving you confidence in every tap or swipe. Without their infrastructure, the seamless experience you enjoy today wouldn’t be possible.
Adapting to the Mobile Payment Landscape
Between traditional banking and digital wallets, financial institutions have had to rethink their strategies to stay relevant. They’ve invested in mobile apps, real-time processing, and user-friendly interfaces to meet your expectations for speed and convenience. By embracing these changes, they’ve made it easier for you to access your funds anytime, anywhere, without compromising security.
Partnerships with Tech Companies
Around the rise of mobile payments, collaborations between banks and tech giants have become a game-changer. These partnerships leverage cutting-edge technology to enhance your experience, from biometric authentication to instant transfers. By working together, they’ve created ecosystems where your transactions feel effortless, whether you’re paying for coffee or splitting rent with friends.
Adapting to the demands of modern consumers, these alliances have also driven innovation in fraud prevention and customer support. You benefit from smarter algorithms that detect unusual activity and round-the-clock assistance, ensuring your money stays protected while moving at the speed of life.
Future Trends in Mobile Payments
Now, mobile payments are evolving faster than ever, with trends like biometric authentication, decentralized finance (DeFi), and AI-driven fraud detection shaping the landscape. You’ll see seamless integration across devices, making transactions quicker and more secure. As digital wallets become smarter, your financial interactions will feel effortless, whether you’re paying bills or splitting costs with friends.
Innovations on the Horizon
Among the breakthroughs you can expect are contactless payments using wearables, like smart rings or glasses, and voice-activated transactions. Blockchain technology will further streamline cross-border payments, reducing fees and wait times. Your mobile wallet might soon predict spending habits, offering personalized discounts before you even check out.
Predictions for Cashout Practices
Innovations in cashout practices will focus on speed and accessibility. You’ll likely see instant transfers becoming the norm, with some platforms offering cashouts in seconds. Peer-to-peer networks and decentralized apps could eliminate intermediaries, putting more control in your hands.
Cashout processes will also become more transparent, with real-time tracking and lower fees. As demand grows, expect competitive rewards for frequent users, like cashback or loyalty points. Your ability to access funds anytime, anywhere, will redefine convenience in mobile finance.
Conclusion
To wrap up, mobile payments have streamlined the way you access your money, turning lengthy transactions into fast cashouts. By leveraging digital wallets and instant transfer features, you can now move funds seamlessly, whether for personal use or business needs. The convenience of tapping your phone eliminates traditional banking delays, putting financial control at your fingertips. As technology evolves, these systems will only grow faster and more secure, ensuring your transactions remain efficient. Adopting mobile payments not only saves time but also enhances your financial flexibility, making it a smart choice for modern money management.
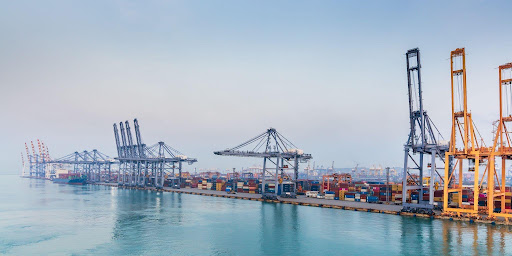
For businesses exporting through Laem Chabang Port, warehouse location is an important factor in managing logistics costs, delivery schedules and supply chain efficiency. The distance between a warehouse and the port can affect trucking time, container turnaround and the ability to meet shipping cut-off times.
As Thailand continues to attract manufacturing investment and strengthen its role in regional supply chains, businesses operating along the Eastern Economic Corridor (EEC) are increasingly considering how warehouse locations fit into their wider logistics networks. For exporters, choosing a site closer to the port can be one way to simplify the movement of goods from storage to shipment, depending on their operational requirements and distribution routes.
In Si Racha, Chonburi, SCX Logistics, the warehouse business of SCX Corporation, is developing its presence near Laem Chabang Port through two sites: Laemchabang 1, which is operating with approximately 47,000 sqm of leasable space, and Laemchabang 2, which is under construction with approximately 42,000 sqm of additional space.
The problem: the road to the port is costing more than the rent
Buyers are asking for shorter lead times. Shipping lines hold firm on cut-offs. And every hour a truck spends between a warehouse and the terminal is an hour paid for. Container trucking near a port is priced by truck time, so a site that allows half as many round trips per shift roughly doubles the truck time behind each box. A delay of an hour on a long run can push a container onto the next sailing, with storage, rebooking and an unhappy buyer to follow.
The pressure lands differently on three groups of businesses now looking at Thailand’s Eastern Seaboard.
Manufacturers relocating to Thailand under China+1. Companies moving part of their production from China need to ship reliably from the first month. Under time pressure, many take the first available warehouse, then find the trip to the port eating the margin they relocated for. Many also need factory space or a custom layout that a standard building does not offer.
Exporters in the Eastern Economic Corridor. Factories in Chonburi and Rayong already sit near the coast, yet finished goods often travel back toward Bangkok for storage before heading to the port. That extra leg adds truck hours, cut-off risk and empty-container moves.
Third-party logistics providers. For a 3PL, port turnaround is the service it sells. Every lost trip per truck is a cost it either absorbs or passes to its own customers. When a client asks for faster export turnaround, the location of the 3PL’s warehouse is often the first thing that limits what it can promise.
How SCX addresses it
SCX’s answer is to put the warehouse where the containers are going. Its Laem Chabang cluster gives each of these groups a different route in.
For China+1 manufacturers, SCX leases both ready-built and built-to-suit space. Ready-built gives a company a proven building on a firm timeline to start shipping. Built-to-suit gives one whose process needs a specific layout a building designed around it. Laemchabang 2 also combines warehouse and factory buildings on one plot, so storage and production can sit side by side.
For EEC exporters, both sites sit in Si Racha District, cutting out the trip back toward Bangkok. Shorter legs between depot, warehouse and terminal also reduce the time an empty container is held, and with it the risk of detention charges.
For 3PLs, Laemchabang 1 is operating now, with buildings from 4,200 to 13,000 sqm in its general zone, while Laemchabang 2 adds capacity in the same district as their contracts grow.
The evidence: what is on the ground
SCX Logistics Laemchabang 1, on Highway 3009 in Si Racha, is operating with around 47,000 sqm of leasable space. SCX Logistics Laemchabang 2, on Nong Khla Mai Road in Bueng, Si Racha, is under construction with around 42,000 sqm. Both are developed with Tokyo Tatemono, SCX’s partner in logistics.
Laemchabang 2 is specified as follows:
| Warehouse | Factory | |
| Floor loading | 4 tons/sqm | 3 tons/sqm |
| Clear height | 12 m | 10 m |
| Floor raised by | +1.30 m | +0.30 m |
| Loading docks | 1 dock and leveller per 1,000 sqm | — |
The 4-ton warehouse floor takes heavy racking and handling equipment directly on the slab. The 12 m clear height lets tenants stack upward before they need more floor area. EV chargers and LED lighting are provided.
The two Laem Chabang sites sit within a wider SCX Logistics portfolio of seven warehouse sites in Thailand, with around 250,000 sqm of leasable space, including two sites on Bangkok’s Bangna–Trad Road corridor. For businesses whose volume goes mainly to customers in Bangkok, SCX can point them there instead. Many operators run both: one base near the port for export, one near the city for domestic delivery.
Quick questions
Why does distance to Laem Chabang Port affect export costs?
Container trucking is priced mainly by truck time. A warehouse closer to the port lets one truck finish more round trips per shift, so the cost of each container falls.
Does SCX have warehouse space near Laem Chabang Port available now?
Yes. SCX Logistics Laemchabang 1 operates on Highway 3009 in Si Racha with around 47,000 sqm of leasable space. Laemchabang 2, on Nong Khla Mai Road in Bueng, is under construction with around 42,000 sqm.
Can manufacturers relocating to Thailand get factory space or a custom layout?
Yes. SCX leases ready-built and built-to-suit space, and Laemchabang 2 combines warehouse and factory buildings on one plot.
What floor loading does Laem Chabang 2 offer?
4 tons per square metre in the warehouse buildings and 3 tons per square metre in the factory buildings, with clear heights of 12 m and 10 m.
About SCX Corporation
SCX Corporation, a subsidiary of SC Asset Corporation Public Company Limited, serves as SC Group’s second engine of growth, building resilient recurring income businesses that support the Group’s long-term sustainable growth. Its portfolio comprises SCX Logistics, SCX Hospitality and SCX Working Solutions, spanning warehouses and logistics facilities, hotels, office properties and clean energy solutions. Guided by its vision, ‘The Prospering Expedition’, and mission, ‘For The Way Forward’, SCX creates long-term value through investment, development and strategic partnerships.
For more information, visit www.scx.co.th.
A credit card is designed to buy things, not to produce cash — yet nearly every card offers some way to turn its limit into money you can hold. Cash advances at ATMs, convenience checks mailed with statements, balance transfers deposited to a bank account, and various informal workarounds all promise the same thing: liquidity now, repayment later. What separates a reasonable emergency tool from an expensive mistake is understanding exactly how each mechanism is priced, where the limits sit, and what alternatives exist before you tap any of them. This guide walks through the mechanics in plain terms.
How a Cash Advance Actually Works
When you withdraw cash against a credit card, you are not making a purchase; you are triggering a separate lending product with its own rules, and those rules are almost universally worse than the ones governing ordinary spending.
Start with the fee. Most issuers charge an upfront cash advance fee, typically calculated as a percentage of the amount withdrawn with a fixed minimum. That fee applies the moment the money leaves the machine, regardless of how quickly you repay.
Then comes the interest treatment, which is where most cardholders get surprised. Purchases usually enjoy a grace period: pay the statement in full and no interest accrues. Cash advances almost never do. Interest begins accumulating on day one, and the rate applied is usually the card’s cash advance APR, which is set meaningfully higher than the purchase APR on the same account. Add the ATM operator’s own surcharge, and the effective cost of holding advance money for even a few weeks becomes substantial.
Limits matter too. The amount available for cash is normally a subset of your total credit line — often a fraction of it — so a card with plenty of open-to-buy may still permit only a modest withdrawal. Issuers also treat heavy cash advance usage as a risk signal. It does not appear as a special mark on your credit report, but it raises utilization, and internally it can influence how a lender views the account.
None of this makes cash advances irrational in every case. For a genuine emergency measured in days, a small advance repaid immediately can be cheaper than a bounced payment or a missed obligation. The product fails people when it becomes routine.
The Gray Zone: Turning Purchases Into Cash
Because official advances are expensive, an informal workaround economy has grown up alongside them: using the card’s purchase function to acquire something easily resold, then converting that item into cash. The most common vehicle is the gift card or prepaid voucher — bought on credit at face value, sold to a buyer or an exchange platform at a discount, with the cardholder pocketing the difference as immediate cash.
This pattern exists worldwide, but it is especially well documented in Korea, where it is common enough to have its own name: consumers there call the practice 신용카드깡, literally the conversion of card credit into cash through merchant transactions or voucher resale. Understanding why the term exists is instructive even for readers elsewhere, because the same economics apply in any market.
The apparent appeal is that a purchase avoids the cash advance fee and, at least initially, the day-one interest clock. The real costs simply move elsewhere. First, the discount: reselling a voucher below face value is itself a fee, frequently comparable to or larger than the official advance fee it replaces. Second, the repayment reality: the full face value lands on your statement, but you received less than face value in cash, so you are repaying money you never got to use. Third, the compliance risk: card networks and issuers prohibit disguised cash-out transactions, and accounts flagged for the pattern can face limit cuts or closure. In several jurisdictions, businesses that facilitate inflated or fictitious transactions for cash-out purposes operate illegally, and consumers who participate can be drawn into disputes with no protection. Finally, there is counterparty risk — handing valuable codes to an unverified buyer is a well-worn scam scenario.
The consumer-education takeaway is not that stored-value markets are inherently bad; legitimate platforms for selling genuinely unwanted gift cards serve a real purpose. The distinction lies in intent and structure. Selling a card you already own and do not need is ordinary liquidation. Systematically buying vouchers on credit in order to manufacture cash is a high-cost loan wearing a disguise, and it should be evaluated — and usually rejected — on exactly those terms.
Cheaper Doors Worth Trying First
Before converting any part of a credit line into cash, walk through the alternatives in rough order of cost.
Ask your employer about earned wage access or a payroll advance; where offered, these are among the cheapest liquidity tools available. Check whether your bank or credit union offers a small-dollar loan or an overdraft line — regulated products whose disclosed rates, while not trivial, are typically far below cash advance territory. A personal loan, even a small one, converts short-term stress into a fixed schedule at a fixed rate. If the need is bill-specific, contact the biller: payment plans for medical, utility, and tax obligations are more available than most people assume, and often interest-free.
If a card must be involved, prefer mechanisms with transparent pricing. A promotional balance transfer deposited to your account discloses its fee upfront. Even a plain cash advance, kept small and repaid within days, at least has the virtue of honest math.
Credit card cash access is best understood as a spectrum of loans that get more expensive as they get more convenient and more opaque. The official advance is costly but visible. The informal conversion route is costly and hidden. The habit that protects you is the same in every country: before taking cash from a card by any door, calculate the true total cost — fees, discounts, and interest to the realistic payoff date — and compare it against one boring alternative. Most of the time, the boring option wins.
In today’s fast-paced world, customer experience (CX) has emerged as a vital ingredient for business success. Companies that prioritize CX not only stand out from the competition but also build lasting relationships with their customers. But what does it take to elevate your customer experience to new heights? Enter BinusCX—a groundbreaking approach designed to innovate and enhance every interaction between businesses and their clients.
Whether you are a seasoned entrepreneur or just starting on your business journey, understanding how BinusCX can reshape your strategy is essential. Get ready to dive into the essentials of this transformative tool, explore its key features, and discover real-world examples of companies reaping its benefits!
Understanding Customer Experience (CX)
Customer experience (CX) refers to the overall perception customers have of a brand based on their interactions. It encompasses every touchpoint, from initial awareness to post-purchase engagement.
At its core, CX is about understanding and meeting customer needs. This means listening actively and responding effectively at each stage of the buyer journey.
A great CX goes beyond mere satisfaction; it creates emotional connections that foster loyalty. Customers who feel valued are likelier to return and recommend your brand.
In today’s digital landscape, expectations are higher than ever. Consumers seek personalized experiences that resonate with them individually.
Businesses need to embrace this shift by creating seamless journeys across multiple channels—whether online or offline. By doing so, they can turn casual buyers into passionate advocates for their brands, paving the way for long-term success in an increasingly competitive market.
The Importance of CX in Business Success
Customer experience (CX) is a vital driver of business success in today’s competitive landscape. Companies that prioritize CX often see enhanced customer loyalty and increased revenue. Satisfied customers are more likely to return and recommend your brand to others.
Moreover, positive experiences can set you apart from competitors. In markets saturated with similar products, exceptional CX becomes a key differentiator. It fosters trust and emotional connections between the consumer and your brand.
Investing in CX not only boosts satisfaction but also reduces churn rates. When customers feel valued, they are less inclined to switch brands for minor advantages elsewhere.
Additionally, effective customer experience strategies provide valuable insights into consumer behavior. Understanding preferences helps businesses adapt their offerings to meet evolving demands, ensuring long-term growth and sustainability within the market.
What is BinusCX and How Does it Work?
BinusCX is an innovative platform designed to enhance customer experience across various business sectors. It leverages advanced technology to streamline interactions between companies and their customers.
The platform uses data analytics to gain insights into customer behavior. This allows businesses to tailor their services for better engagement. By identifying trends, BinusCX helps organizations anticipate needs before they arise.
Users can access multiple tools within the platform. These include feedback loops, journey mapping, and performance metrics. Each feature empowers teams to make informed decisions based on real-time information.
Integration with existing systems is seamless, ensuring that businesses don’t face disruption during implementation. With BinusCX, companies can foster a culture of continuous improvement in customer relations while staying ahead of market demands.
Key Features and Benefits of BinusCX
BinusCX stands out with its user-friendly interface, making it easy for businesses to navigate. This simplicity encourages teams to engage more deeply with the platform.
Another key feature is real-time analytics. Companies can track customer interactions as they happen, allowing for swift adjustments in strategy. Data-driven decisions become a breeze.
Customization options are abundant, enabling brands to tailor their CX solutions according to specific needs. This flexibility is crucial in today’s diverse market landscape.
Moreover, BinusCX promotes seamless integration with existing systems. Businesses can enhance their current workflows without disruptive overhauls or significant downtime.
Collaboration tools within BinusCX foster teamwork among departments. A unified approach ensures that everyone from marketing to support works toward a shared vision of exceptional customer experience.
Continuous updates and enhancements keep the platform ahead of industry trends, ensuring users benefit from the latest innovations in customer experience management.
Case Studies: How Companies Have Utilized BinusCX to Improve CX
Several companies have successfully harnessed the power of BinusCX to elevate their customer experience.
A leading retail brand utilized BinusCX analytics to identify pain points in their shopping journey. By implementing personalized recommendations, they saw a 20% increase in conversion rates within just three months.
In the hospitality sector, a hotel chain adopted BinusCX for real-time feedback from guests. This proactive approach enabled them to address complaints immediately, resulting in increased guest satisfaction scores and positive reviews across online platforms.
Another tech startup integrated BinusCX to streamline its customer support process. With automated responses and an intuitive interface, response times decreased by over 30%, allowing agents to focus on complex issues.
These case studies illustrate how diverse industries leverage BinusCX as a catalyst for improvement. Each organization was able to tailor strategies that align with their unique goals while enhancing overall engagement with customers.
Implementation and Integration of BinusCX in Your Business
Implementing BinusCX in your business can be a transformative experience. Start by evaluating your current customer experience strategy. Identify areas that need improvement, and set clear goals for what you want to achieve with BinusCX.
Next, integrate the platform with your existing systems. This could involve syncing tools like CRM software or marketing automation platforms. Seamless integration is crucial for maximizing efficiency.
Training your team is essential as well. Ensure they understand how to use BinusCX effectively and are familiar with its features. Conduct workshops or provide resources to facilitate this learning process.
Monitor progress regularly. Use data analytics provided by BinusCX to assess improvements in customer satisfaction and engagement levels. Continuous assessment will help refine strategies over time, ensuring long-term success in enhancing customer experiences.
Conclusion
Customer experience is a vital aspect of any successful business strategy. Understanding and enhancing CX can lead to lasting customer loyalty, increased revenue, and a strong market presence. BinusCX emerges as an innovative solution in this landscape, offering tools designed for businesses eager to elevate their customer interactions.
The platform’s features provide powerful insights that guide companies towards making informed decisions. By leveraging data analytics and user-friendly interfaces, BinusCX empowers organizations to understand their customers better than ever before.
As illustrated through various case studies, many businesses have transformed their CX practices by integrating BinusCX into their operations. The results speak volumes: improved satisfaction rates and higher retention levels showcase the tangible benefits of adopting this approach.
-
 HEALTH3 years ago
Transformative Health Solutions: Unveiling the Breakthroughs of 10x Health
-
 Posts3 years ago
Siegel, Cooper & Co.
-
 GENERAL3 years ago
Discovering the Artistic Brilliance of Derpixon: A Deep Dive into their Animation and Illustration
-
 Lifestyle3 years ago
Purenudism.com: Unveiling the Beauty of Naturist Lifestyle
-
 FASHION3 years ago
The Many Faces of “λιβαισ”: A Comprehensive Guide to its Symbolism in Different Cultures
-
 Lifestyle3 years ago
BaddieHub: Unleashing Confidence and Style in the Ultimate Gathering Spot for the Baddie Lifestyle
-
 Home improvement2 years ago
Unleash Your Creative Side: Exploring Stylish Rug Collections to Elevate Your Space with Quality Rug & Carpet Options
-
 PETS2 years ago
From Bows to Bandanas: Elevate Your Dog’s Style Game with These Trendy Accessories