BUSINESS
Maximizing Information Fee Cashing with Google: What You Need to Know

Managing finances efficiently is essential for both businesses and individuals. One of the quickest ways to access funds is through Google’s information fee cashing. Whether it’s from Google Ads, Google Play, or other services, cashing out information fees offers flexibility and ease of access. In this post, we’ll explore what online card cashing services are, how they work, their benefits, and the potential risks to keep in mind.
What are Online Card Cashing Services?
Online card cashing services allow individuals or businesses to access cash quickly by using their credit cards, processed through an online platform. This service provides a fast solution to those who need funds for operational expenses, emergency payments, or short-term cash needs.
Definition and Overview of Online Card Cashing
Online card cashing involves converting a credit card’s available limit into liquid cash, often through a third-party platform. These services work by facilitating the transfer of credit into cash, which is then deposited into the user’s bank account or provided as a physical withdrawal.
- How it Works: The user simply logs into an online platform, inputs their credit card information, and requests a cash advance or a transaction. A small fee is deducted, and the remaining amount is credited to the user’s account or given in cash.
- Why It’s Popular: This service is popular because it provides immediate access to funds without the need for traditional loans or credit approval processes.
How Online Card Cashing Differs from Traditional Methods
Online card cashing differs from traditional methods like credit card advances in several key ways:
- Convenience: Unlike traditional credit card cash advances, which require a visit to a bank or ATM, online card cashing can be done remotely, saving time and effort.
- Lower Fees: Many online services offer lower fees compared to traditional methods, which can often have high transaction fees and interest rates.
- Faster Access to Funds: Online card cashing services typically provide faster processing, often transferring funds to a user’s bank account within hours, compared to several days for traditional options.
When and Why to Use Online Card Cashing Services
Online card cashing services are especially useful for businesses 정보이용료 현금화 and individuals facing short-term cash flow issues. Here’s why they might be used:
- Emergency Financial Needs: Online card cashing provides quick access to funds, making it a perfect option for emergency expenses like medical bills or urgent business costs.
- Low-Cost Alternative: For those unable to secure loans or other forms of financing, online card cashing offers a cost-effective solution, especially with lower transaction fees compared to payday loans or traditional credit advances.
- Convenience and Accessibility: The ability to access funds remotely makes online card cashing an appealing option for people who are unable to visit a physical location.
Benefits and Risks of Online Card Cashing Services
While online card cashing offers several benefits, it also carries certain risks. Understanding both sides of the equation is crucial before deciding to use this service.
Benefits of Online Card Cashing Services
There are many reasons why people use online card cashing services, particularly when they need quick and flexible access to funds.
- Quick and Easy Access to Funds: One of the most significant benefits of online card cashing is speed. Users can access cash within hours, which is much faster than applying for loans or waiting for approval from traditional banking institutions.
- Lower Transaction Fees: Compared to traditional credit card cash advances or payday loans, many online card cashing services have lower fees, which makes them a more affordable option in emergency situations.
- Flexibility and Convenience: Online platforms provide the flexibility to request cash at any time and from anywhere, making it highly convenient for individuals and businesses alike.
Potential Risks and Challenges
Despite its benefits, online card cashing comes with potential downsides that users should be aware of.
- High Interest Rates: Credit card cash advances often come with high interest rates. If the balance is not repaid quickly, the interest can quickly accrue, making the service costly.
- Security Concerns: Providing sensitive credit card information to online platforms increases the risk of fraud and data breaches. It is crucial to choose trusted and secure services to avoid compromising personal or business data.
- Legal and Regulatory Risks: In some jurisdictions, credit card cashing may be subject to legal restrictions. It’s important to be aware of the legal landscape in your region and use services that comply with applicable laws to avoid any legal repercussions.
By understanding these risks, you can make more informed decisions about whether online card cashing services are right for your financial needs.
FAQ – Common Questions About Online Card Cashing Services
1. What are online card cashing services?
Online card cashing services allow individuals and businesses to access cash by using their credit cards, processed through online platforms. The service facilitates the conversion of credit into cash, which is deposited into your bank account or given to you after deducting a small fee.
2. How do online card cashing services work?
Users simply need to provide their credit card details to an online platform, request a cash advance, and receive the funds after the platform processes the transaction. Fees are deducted, typically leaving the user with 92% or more of the original amount.
3. What are the benefits of online card cashing services?
Some of the key benefits include quick access to cash, lower fees compared to traditional methods, and the convenience of accessing funds remotely. This service is ideal for urgent financial needs and offers flexibility for individuals and businesses.
4. Are there any risks involved?
Yes, some risks include high interest rates, security concerns, and potential legal issues if not used correctly. It’s important to choose reputable services and manage cash advances carefully to avoid accumulating excessive debt.
5. When should I use online card cashing services?
Online card cashing services are best used for short-term financial needs, such as urgent business expenses or personal emergencies. It is not recommended as a long-term financial solution, as the costs can add up over time.
Conclusion
In conclusion, online card cashing services offer a convenient and efficient way to access cash quickly, making them ideal for businesses and individuals facing urgent financial needs. With benefits such as quick access to funds and lower transaction fees, these services provide flexibility and financial relief. However, it’s essential to be aware of the risks, including high interest rates, security concerns, and potential legal issues. By choosing reputable services and using card cashing responsibly, users can minimize risks and make the most of these services while ensuring long-term financial health.
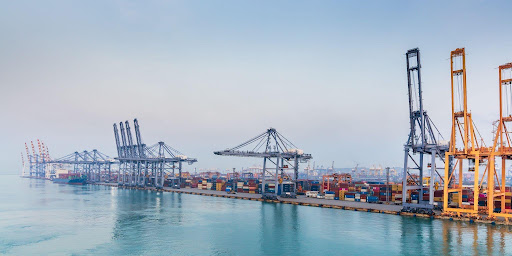
For businesses exporting through Laem Chabang Port, warehouse location is an important factor in managing logistics costs, delivery schedules and supply chain efficiency. The distance between a warehouse and the port can affect trucking time, container turnaround and the ability to meet shipping cut-off times.
As Thailand continues to attract manufacturing investment and strengthen its role in regional supply chains, businesses operating along the Eastern Economic Corridor (EEC) are increasingly considering how warehouse locations fit into their wider logistics networks. For exporters, choosing a site closer to the port can be one way to simplify the movement of goods from storage to shipment, depending on their operational requirements and distribution routes.
In Si Racha, Chonburi, SCX Logistics, the warehouse business of SCX Corporation, is developing its presence near Laem Chabang Port through two sites: Laemchabang 1, which is operating with approximately 47,000 sqm of leasable space, and Laemchabang 2, which is under construction with approximately 42,000 sqm of additional space.
The problem: the road to the port is costing more than the rent
Buyers are asking for shorter lead times. Shipping lines hold firm on cut-offs. And every hour a truck spends between a warehouse and the terminal is an hour paid for. Container trucking near a port is priced by truck time, so a site that allows half as many round trips per shift roughly doubles the truck time behind each box. A delay of an hour on a long run can push a container onto the next sailing, with storage, rebooking and an unhappy buyer to follow.
The pressure lands differently on three groups of businesses now looking at Thailand’s Eastern Seaboard.
Manufacturers relocating to Thailand under China+1. Companies moving part of their production from China need to ship reliably from the first month. Under time pressure, many take the first available warehouse, then find the trip to the port eating the margin they relocated for. Many also need factory space or a custom layout that a standard building does not offer.
Exporters in the Eastern Economic Corridor. Factories in Chonburi and Rayong already sit near the coast, yet finished goods often travel back toward Bangkok for storage before heading to the port. That extra leg adds truck hours, cut-off risk and empty-container moves.
Third-party logistics providers. For a 3PL, port turnaround is the service it sells. Every lost trip per truck is a cost it either absorbs or passes to its own customers. When a client asks for faster export turnaround, the location of the 3PL’s warehouse is often the first thing that limits what it can promise.
How SCX addresses it
SCX’s answer is to put the warehouse where the containers are going. Its Laem Chabang cluster gives each of these groups a different route in.
For China+1 manufacturers, SCX leases both ready-built and built-to-suit space. Ready-built gives a company a proven building on a firm timeline to start shipping. Built-to-suit gives one whose process needs a specific layout a building designed around it. Laemchabang 2 also combines warehouse and factory buildings on one plot, so storage and production can sit side by side.
For EEC exporters, both sites sit in Si Racha District, cutting out the trip back toward Bangkok. Shorter legs between depot, warehouse and terminal also reduce the time an empty container is held, and with it the risk of detention charges.
For 3PLs, Laemchabang 1 is operating now, with buildings from 4,200 to 13,000 sqm in its general zone, while Laemchabang 2 adds capacity in the same district as their contracts grow.
The evidence: what is on the ground
SCX Logistics Laemchabang 1, on Highway 3009 in Si Racha, is operating with around 47,000 sqm of leasable space. SCX Logistics Laemchabang 2, on Nong Khla Mai Road in Bueng, Si Racha, is under construction with around 42,000 sqm. Both are developed with Tokyo Tatemono, SCX’s partner in logistics.
Laemchabang 2 is specified as follows:
| Warehouse | Factory | |
| Floor loading | 4 tons/sqm | 3 tons/sqm |
| Clear height | 12 m | 10 m |
| Floor raised by | +1.30 m | +0.30 m |
| Loading docks | 1 dock and leveller per 1,000 sqm | — |
The 4-ton warehouse floor takes heavy racking and handling equipment directly on the slab. The 12 m clear height lets tenants stack upward before they need more floor area. EV chargers and LED lighting are provided.
The two Laem Chabang sites sit within a wider SCX Logistics portfolio of seven warehouse sites in Thailand, with around 250,000 sqm of leasable space, including two sites on Bangkok’s Bangna–Trad Road corridor. For businesses whose volume goes mainly to customers in Bangkok, SCX can point them there instead. Many operators run both: one base near the port for export, one near the city for domestic delivery.
Quick questions
Why does distance to Laem Chabang Port affect export costs?
Container trucking is priced mainly by truck time. A warehouse closer to the port lets one truck finish more round trips per shift, so the cost of each container falls.
Does SCX have warehouse space near Laem Chabang Port available now?
Yes. SCX Logistics Laemchabang 1 operates on Highway 3009 in Si Racha with around 47,000 sqm of leasable space. Laemchabang 2, on Nong Khla Mai Road in Bueng, is under construction with around 42,000 sqm.
Can manufacturers relocating to Thailand get factory space or a custom layout?
Yes. SCX leases ready-built and built-to-suit space, and Laemchabang 2 combines warehouse and factory buildings on one plot.
What floor loading does Laem Chabang 2 offer?
4 tons per square metre in the warehouse buildings and 3 tons per square metre in the factory buildings, with clear heights of 12 m and 10 m.
About SCX Corporation
SCX Corporation, a subsidiary of SC Asset Corporation Public Company Limited, serves as SC Group’s second engine of growth, building resilient recurring income businesses that support the Group’s long-term sustainable growth. Its portfolio comprises SCX Logistics, SCX Hospitality and SCX Working Solutions, spanning warehouses and logistics facilities, hotels, office properties and clean energy solutions. Guided by its vision, ‘The Prospering Expedition’, and mission, ‘For The Way Forward’, SCX creates long-term value through investment, development and strategic partnerships.
For more information, visit www.scx.co.th.
A credit card is designed to buy things, not to produce cash — yet nearly every card offers some way to turn its limit into money you can hold. Cash advances at ATMs, convenience checks mailed with statements, balance transfers deposited to a bank account, and various informal workarounds all promise the same thing: liquidity now, repayment later. What separates a reasonable emergency tool from an expensive mistake is understanding exactly how each mechanism is priced, where the limits sit, and what alternatives exist before you tap any of them. This guide walks through the mechanics in plain terms.
How a Cash Advance Actually Works
When you withdraw cash against a credit card, you are not making a purchase; you are triggering a separate lending product with its own rules, and those rules are almost universally worse than the ones governing ordinary spending.
Start with the fee. Most issuers charge an upfront cash advance fee, typically calculated as a percentage of the amount withdrawn with a fixed minimum. That fee applies the moment the money leaves the machine, regardless of how quickly you repay.
Then comes the interest treatment, which is where most cardholders get surprised. Purchases usually enjoy a grace period: pay the statement in full and no interest accrues. Cash advances almost never do. Interest begins accumulating on day one, and the rate applied is usually the card’s cash advance APR, which is set meaningfully higher than the purchase APR on the same account. Add the ATM operator’s own surcharge, and the effective cost of holding advance money for even a few weeks becomes substantial.
Limits matter too. The amount available for cash is normally a subset of your total credit line — often a fraction of it — so a card with plenty of open-to-buy may still permit only a modest withdrawal. Issuers also treat heavy cash advance usage as a risk signal. It does not appear as a special mark on your credit report, but it raises utilization, and internally it can influence how a lender views the account.
None of this makes cash advances irrational in every case. For a genuine emergency measured in days, a small advance repaid immediately can be cheaper than a bounced payment or a missed obligation. The product fails people when it becomes routine.
The Gray Zone: Turning Purchases Into Cash
Because official advances are expensive, an informal workaround economy has grown up alongside them: using the card’s purchase function to acquire something easily resold, then converting that item into cash. The most common vehicle is the gift card or prepaid voucher — bought on credit at face value, sold to a buyer or an exchange platform at a discount, with the cardholder pocketing the difference as immediate cash.
This pattern exists worldwide, but it is especially well documented in Korea, where it is common enough to have its own name: consumers there call the practice 신용카드깡, literally the conversion of card credit into cash through merchant transactions or voucher resale. Understanding why the term exists is instructive even for readers elsewhere, because the same economics apply in any market.
The apparent appeal is that a purchase avoids the cash advance fee and, at least initially, the day-one interest clock. The real costs simply move elsewhere. First, the discount: reselling a voucher below face value is itself a fee, frequently comparable to or larger than the official advance fee it replaces. Second, the repayment reality: the full face value lands on your statement, but you received less than face value in cash, so you are repaying money you never got to use. Third, the compliance risk: card networks and issuers prohibit disguised cash-out transactions, and accounts flagged for the pattern can face limit cuts or closure. In several jurisdictions, businesses that facilitate inflated or fictitious transactions for cash-out purposes operate illegally, and consumers who participate can be drawn into disputes with no protection. Finally, there is counterparty risk — handing valuable codes to an unverified buyer is a well-worn scam scenario.
The consumer-education takeaway is not that stored-value markets are inherently bad; legitimate platforms for selling genuinely unwanted gift cards serve a real purpose. The distinction lies in intent and structure. Selling a card you already own and do not need is ordinary liquidation. Systematically buying vouchers on credit in order to manufacture cash is a high-cost loan wearing a disguise, and it should be evaluated — and usually rejected — on exactly those terms.
Cheaper Doors Worth Trying First
Before converting any part of a credit line into cash, walk through the alternatives in rough order of cost.
Ask your employer about earned wage access or a payroll advance; where offered, these are among the cheapest liquidity tools available. Check whether your bank or credit union offers a small-dollar loan or an overdraft line — regulated products whose disclosed rates, while not trivial, are typically far below cash advance territory. A personal loan, even a small one, converts short-term stress into a fixed schedule at a fixed rate. If the need is bill-specific, contact the biller: payment plans for medical, utility, and tax obligations are more available than most people assume, and often interest-free.
If a card must be involved, prefer mechanisms with transparent pricing. A promotional balance transfer deposited to your account discloses its fee upfront. Even a plain cash advance, kept small and repaid within days, at least has the virtue of honest math.
Credit card cash access is best understood as a spectrum of loans that get more expensive as they get more convenient and more opaque. The official advance is costly but visible. The informal conversion route is costly and hidden. The habit that protects you is the same in every country: before taking cash from a card by any door, calculate the true total cost — fees, discounts, and interest to the realistic payoff date — and compare it against one boring alternative. Most of the time, the boring option wins.
In today’s fast-paced world, customer experience (CX) has emerged as a vital ingredient for business success. Companies that prioritize CX not only stand out from the competition but also build lasting relationships with their customers. But what does it take to elevate your customer experience to new heights? Enter BinusCX—a groundbreaking approach designed to innovate and enhance every interaction between businesses and their clients.
Whether you are a seasoned entrepreneur or just starting on your business journey, understanding how BinusCX can reshape your strategy is essential. Get ready to dive into the essentials of this transformative tool, explore its key features, and discover real-world examples of companies reaping its benefits!
Understanding Customer Experience (CX)
Customer experience (CX) refers to the overall perception customers have of a brand based on their interactions. It encompasses every touchpoint, from initial awareness to post-purchase engagement.
At its core, CX is about understanding and meeting customer needs. This means listening actively and responding effectively at each stage of the buyer journey.
A great CX goes beyond mere satisfaction; it creates emotional connections that foster loyalty. Customers who feel valued are likelier to return and recommend your brand.
In today’s digital landscape, expectations are higher than ever. Consumers seek personalized experiences that resonate with them individually.
Businesses need to embrace this shift by creating seamless journeys across multiple channels—whether online or offline. By doing so, they can turn casual buyers into passionate advocates for their brands, paving the way for long-term success in an increasingly competitive market.
The Importance of CX in Business Success
Customer experience (CX) is a vital driver of business success in today’s competitive landscape. Companies that prioritize CX often see enhanced customer loyalty and increased revenue. Satisfied customers are more likely to return and recommend your brand to others.
Moreover, positive experiences can set you apart from competitors. In markets saturated with similar products, exceptional CX becomes a key differentiator. It fosters trust and emotional connections between the consumer and your brand.
Investing in CX not only boosts satisfaction but also reduces churn rates. When customers feel valued, they are less inclined to switch brands for minor advantages elsewhere.
Additionally, effective customer experience strategies provide valuable insights into consumer behavior. Understanding preferences helps businesses adapt their offerings to meet evolving demands, ensuring long-term growth and sustainability within the market.
What is BinusCX and How Does it Work?
BinusCX is an innovative platform designed to enhance customer experience across various business sectors. It leverages advanced technology to streamline interactions between companies and their customers.
The platform uses data analytics to gain insights into customer behavior. This allows businesses to tailor their services for better engagement. By identifying trends, BinusCX helps organizations anticipate needs before they arise.
Users can access multiple tools within the platform. These include feedback loops, journey mapping, and performance metrics. Each feature empowers teams to make informed decisions based on real-time information.
Integration with existing systems is seamless, ensuring that businesses don’t face disruption during implementation. With BinusCX, companies can foster a culture of continuous improvement in customer relations while staying ahead of market demands.
Key Features and Benefits of BinusCX
BinusCX stands out with its user-friendly interface, making it easy for businesses to navigate. This simplicity encourages teams to engage more deeply with the platform.
Another key feature is real-time analytics. Companies can track customer interactions as they happen, allowing for swift adjustments in strategy. Data-driven decisions become a breeze.
Customization options are abundant, enabling brands to tailor their CX solutions according to specific needs. This flexibility is crucial in today’s diverse market landscape.
Moreover, BinusCX promotes seamless integration with existing systems. Businesses can enhance their current workflows without disruptive overhauls or significant downtime.
Collaboration tools within BinusCX foster teamwork among departments. A unified approach ensures that everyone from marketing to support works toward a shared vision of exceptional customer experience.
Continuous updates and enhancements keep the platform ahead of industry trends, ensuring users benefit from the latest innovations in customer experience management.
Case Studies: How Companies Have Utilized BinusCX to Improve CX
Several companies have successfully harnessed the power of BinusCX to elevate their customer experience.
A leading retail brand utilized BinusCX analytics to identify pain points in their shopping journey. By implementing personalized recommendations, they saw a 20% increase in conversion rates within just three months.
In the hospitality sector, a hotel chain adopted BinusCX for real-time feedback from guests. This proactive approach enabled them to address complaints immediately, resulting in increased guest satisfaction scores and positive reviews across online platforms.
Another tech startup integrated BinusCX to streamline its customer support process. With automated responses and an intuitive interface, response times decreased by over 30%, allowing agents to focus on complex issues.
These case studies illustrate how diverse industries leverage BinusCX as a catalyst for improvement. Each organization was able to tailor strategies that align with their unique goals while enhancing overall engagement with customers.
Implementation and Integration of BinusCX in Your Business
Implementing BinusCX in your business can be a transformative experience. Start by evaluating your current customer experience strategy. Identify areas that need improvement, and set clear goals for what you want to achieve with BinusCX.
Next, integrate the platform with your existing systems. This could involve syncing tools like CRM software or marketing automation platforms. Seamless integration is crucial for maximizing efficiency.
Training your team is essential as well. Ensure they understand how to use BinusCX effectively and are familiar with its features. Conduct workshops or provide resources to facilitate this learning process.
Monitor progress regularly. Use data analytics provided by BinusCX to assess improvements in customer satisfaction and engagement levels. Continuous assessment will help refine strategies over time, ensuring long-term success in enhancing customer experiences.
Conclusion
Customer experience is a vital aspect of any successful business strategy. Understanding and enhancing CX can lead to lasting customer loyalty, increased revenue, and a strong market presence. BinusCX emerges as an innovative solution in this landscape, offering tools designed for businesses eager to elevate their customer interactions.
The platform’s features provide powerful insights that guide companies towards making informed decisions. By leveraging data analytics and user-friendly interfaces, BinusCX empowers organizations to understand their customers better than ever before.
As illustrated through various case studies, many businesses have transformed their CX practices by integrating BinusCX into their operations. The results speak volumes: improved satisfaction rates and higher retention levels showcase the tangible benefits of adopting this approach.
-
 HEALTH3 years ago
Transformative Health Solutions: Unveiling the Breakthroughs of 10x Health
-
 Posts3 years ago
Siegel, Cooper & Co.
-
 GENERAL3 years ago
Discovering the Artistic Brilliance of Derpixon: A Deep Dive into their Animation and Illustration
-
 Lifestyle3 years ago
Purenudism.com: Unveiling the Beauty of Naturist Lifestyle
-
 FASHION3 years ago
The Many Faces of “λιβαισ”: A Comprehensive Guide to its Symbolism in Different Cultures
-
 Lifestyle3 years ago
BaddieHub: Unleashing Confidence and Style in the Ultimate Gathering Spot for the Baddie Lifestyle
-
 Home improvement2 years ago
Unleash Your Creative Side: Exploring Stylish Rug Collections to Elevate Your Space with Quality Rug & Carpet Options
-
 PETS2 years ago
From Bows to Bandanas: Elevate Your Dog’s Style Game with These Trendy Accessories